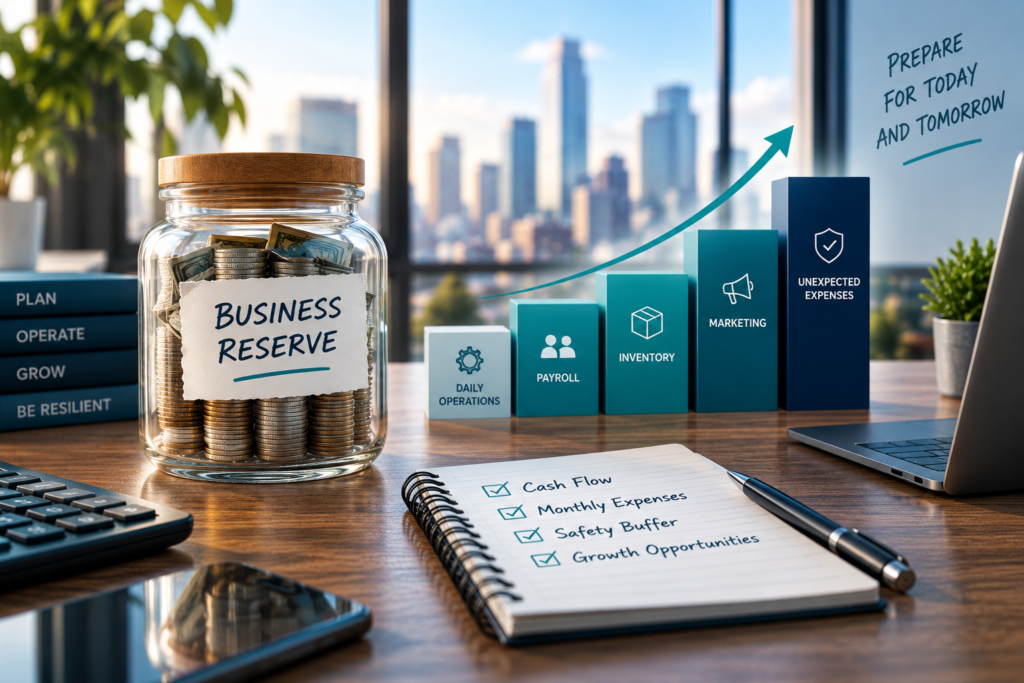
Working capital is the lifeblood of any small business. It covers payroll, inventory, rent, and every operational expense that keeps the doors open between the time money goes out and revenue comes back in. The question most business owners wrestle with is not whether to keep a reserve — it is how much.
There is no single number that works for every business. But there are proven frameworks that help you land on a figure that protects your operations without leaving too much cash sitting idle.
The Standard Benchmark: Two to Six Months of Operating Expenses
The most widely cited guideline is to keep enough working capital to cover two to six months of operating expenses. That range exists because businesses vary dramatically in their cash flow patterns, industry cycles, and risk exposure.
A business with predictable, recurring revenue — a subscription service or a long-term contract holder — can operate comfortably toward the lower end. A business with seasonal swings, long invoice payment cycles, or a concentrated customer base needs to sit closer to the higher end.
Your Working Capital Ratio Tells the Real Story
Before deciding how much to keep in reserve, you need to know where you stand right now. Your working capital ratio — also called the current ratio — gives you that snapshot.
The formula is straightforward: divide your current assets by your current liabilities. A ratio between 1.2 and 2.0 is generally considered healthy for a small business. Below 1.0 means your short-term liabilities exceed your short-term assets, which is a warning sign. Above 2.0 may indicate you are holding too much cash that could be deployed more productively.
Factors That Should Shift Your Target
The right reserve level for your business depends on several variables that go beyond generic benchmarks.
Revenue Seasonality
If a significant portion of your annual revenue arrives in a compressed window, you need reserves large enough to sustain operations during the slow months without relying on credit. Retailers, landscapers, and tax preparers all face this reality.
Payment Terms and Receivables Cycles
When customers pay on net-30, net-60, or net-90 terms, there is a gap between when you deliver and when you collect. The longer that gap, the larger your reserve needs to be to bridge it without disrupting operations.
Industry Volatility
Industries exposed to commodity price swings, regulatory shifts, or demand fluctuations require deeper reserves. Construction, hospitality, and transportation businesses carry inherently higher operational uncertainty than others.
Growth Stage
Businesses in active growth mode spend more before they earn more. Hiring, equipment, inventory buildup, and marketing all precede the revenue they generate. If you are scaling, your reserve target should reflect that elevated burn rate.
Access to Credit
If you have a reliable line of credit you can draw on quickly, you may be able to hold a leaner cash reserve. If your financing options are limited or untested, you need more liquidity on hand.
A Practical Way to Calculate Your Number
Start by calculating your average monthly operating expenses. Include payroll, rent, utilities, insurance, loan payments, supplier costs, and any recurring overhead. Do not include one-time capital expenditures in this figure.
Then multiply that monthly figure by the number of months your situation demands. A service business with steady contracts and strong receivables management might target three months. A product-based business with seasonal demand and 60-day payment terms might target five.
That calculation gives you a tangible reserve target — not a guess, but a number grounded in your actual cost structure.
Where to Keep Your Working Capital Reserve
Holding reserves in a standard checking account is convenient but leaves money working below its potential. Consider a high-yield business savings account or a money market account that keeps funds accessible while generating modest returns. The goal is liquidity first, yield second — your reserve has to be available when you need it without delay.
When Your Reserve Falls Short
Even well-managed businesses hit periods where reserves are not enough. A large order requires upfront inventory investment. A key customer pays late. An unexpected expense lands at the wrong time.
That is where working capital financing becomes a strategic tool rather than a last resort. A business line of credit, invoice financing, or a short-term working capital loan can fill the gap without forcing you to sacrifice long-term assets or miss opportunities.
The businesses that handle these moments best are not the ones with infinite cash — they are the ones who planned for the gap and had financing options ready before the pressure arrived.
Reserve Management Is an Ongoing Practice
Setting a target is step one. Maintaining it requires discipline. Review your working capital position monthly, not quarterly. Adjust your target as your business grows, your cost structure changes, or your market shifts. Treat your reserve as a dynamic tool, not a static number.
The businesses that survive downturns, seize opportunities, and scale without crisis are the ones that take working capital seriously before they have to. Set your target, build toward it, and know exactly where to turn when you need additional support.
Keen Funding works with small businesses to structure working capital solutions that fit real operational needs. If your reserves are stretched or you want to explore your options before you need them, reach out to our team today.